The Hidden Math of Relocation:
How to Vet Your Next Best Place Before Packing a Single Box
Every year, thousands of retirees pull up stakes, sell the family home, and move toward an idealized version of their future. They target a sunny climate, lower headline taxes, or a relaxed coastal town where life promises to feel less hectic.
Two years later, an alarming percentage of those same people find themselves frustrated, isolated, or financially strained.
The mistake rarely comes from a lack of enthusiasm. It comes from treating relocation like an extended vacation instead of what it truly is: an irreversible capital reallocation and a complete overhaul of your daily operational life. When you move across state lines or even two counties over in retirement, you are trading an established network of doctors, friends, service providers, and tax baselines for a set of unknowns.
If you make that leap without running the hard numbers first, the frictional costs of fixing the error can permanently damage your nest egg. Selling a home, moving cross-country, buying another property, realizing it was a mistake, and attempting to pivot back can easily burn through $80,000 to $120,000 in closing costs, agent fees, physical moving expenses, and local transfer taxes.
Finding your Next Best Place requires stepping back from the marketing gloss, ignoring regional cheerleading, and evaluating target destinations through a cold, analytical lens.
The Aggregate Tax Trap: Looking Beyond Zero Income Tax
The single largest misconception driving retirement migration is the belief that zero state income tax automatically translates to low-cost living.
States have basic operational obligations: roads, schools, emergency services, law enforcement, and municipal infrastructure. If a state chooses not to tax income, it must generate that revenue elsewhere. That revenue almost always comes through aggressive property assessments, high sales taxes, elevated vehicle registration fees, or specialized county levies.
Consider how different states structure their revenue models:
Texas: No personal income tax, but property taxes frequently land between 1.6% and 2.2% or higher. On a $500,000 home, an annual property tax bill can easily run $8,000 to $11,000.
Florida: No personal income tax, but newcomers often face a severe property tax shock. While long-term residents benefit from homestead assessment caps, a newly purchased home is reassessed at current market value the following January. Combined with surging hazard and flood insurance premiums, monthly carrying costs can quickly outpace expectations.
South Carolina: Has a graduated state income tax, but offers significant retirement income exemptions and caps owner-occupied primary residence property taxes at an effective rate that often keeps annual taxes on a $500,000 home under $2,500.
Tennessee: No state income tax, but state and local sales taxes routinely push past 9.5% on retail goods and everyday consumer items.
To evaluate a destination properly, you must calculate your aggregate household tax liability. That means sitting down with your actual retirement budget and calculating:
Retirement Income Exposure: Does the state tax traditional IRA and 401(k) withdrawals, public pensions, private pensions, or Social Security benefits?
True Property Tax Post-Sale: What will the county reassessment look like based on your target purchase price, rather than what the seller currently pays?
Sales and Local Option Taxes: What is the actual combined rate on purchases, dining, and home improvements in that specific municipality?
Vehicular and Personal Property Taxes: Does the state levy an annual ad valorem tax on vehicles, boats, or RVs just for the privilege of keeping them parked in your driveway?
A zero-income-tax state may save you money if you have massive taxable distributions, but for a moderate-income retiree relying heavily on Social Security and modest portfolio withdrawals, high property and sales taxes can result in a higher overall net tax bill.
The Phantom Carrying Costs: Insurance, Maintenance, and HOAs
A generation ago, calculating housing costs was simple: principal, interest, basic property tax, and nominal hazard insurance. Today, structural carrying costs have decoupled from home prices. In rapid-migration corridors, insurance and association fees are shifting monthly budgets by hundreds of dollars.
The Realities of Home Insurance
Between reinsurance rate increases and shifting weather risk models, homeowners insurance has become a primary deal-breaker in popular Sunbelt and coastal markets. Before you fall in love with a floor plan, pull an address-specific insurance quote.
Wind and Hail Deductibles: Many policies in southern and coastal markets no longer use standard $1,000 deductibles. Instead, they require percentage-based deductibles (often 2% to 5% of the dwelling's insured value) for named storms. On a $500,000 dwelling limit, a 2% hurricane deductible means you pay $10,000 out of pocket before coverage starts.
Flood Zones and Base Flood Elevations: A home does not need to be on the beach to require flood insurance. Low-lying developments inland can carry mandatory flood insurance requirements with steep annual premiums. Always verify the current FEMA flood zone designation and check whether the community has experienced localized street flooding during regular heavy rains.
HOA Health and Reserve Studies
Master-planned communities with clubhouses, pickleball courts, gatehouses, and extensive landscaping look exceptional on a tour. However, every square foot of shared asphalt, every community pool pump, and every retention pond represents a future liability.
If you are considering an HOA-managed community, do not settle for reviewing the current monthly fee. Request and read the latest professional reserve study:
Funded Ratio: Is the reserve account funded at 70% or higher? If a community has a 35% funded reserve, the HOA will inevitably issue a multi-thousand-dollar special assessment to repair streets, replace roofs, or overhaul amenities.
Historical Dues Escalation: How much have dues risen over the past four years? Communities that kept dues artificially low to attract early buyers frequently face massive percentage increases as the neighborhood reaches full build-out.
Rental and Commercial Restrictions: Ensure the bylaws protect owner occupancy rates while retaining reasonable flexibility should your family situation change.
The Clinical Capacity Gap: Testing Local Healthcare
When evaluating potential destinations, most people check whether there is a reputable hospital within a thirty-minute drive. While proximity to a regional medical center matters, it tells you very little about your day-to-day healthcare access.
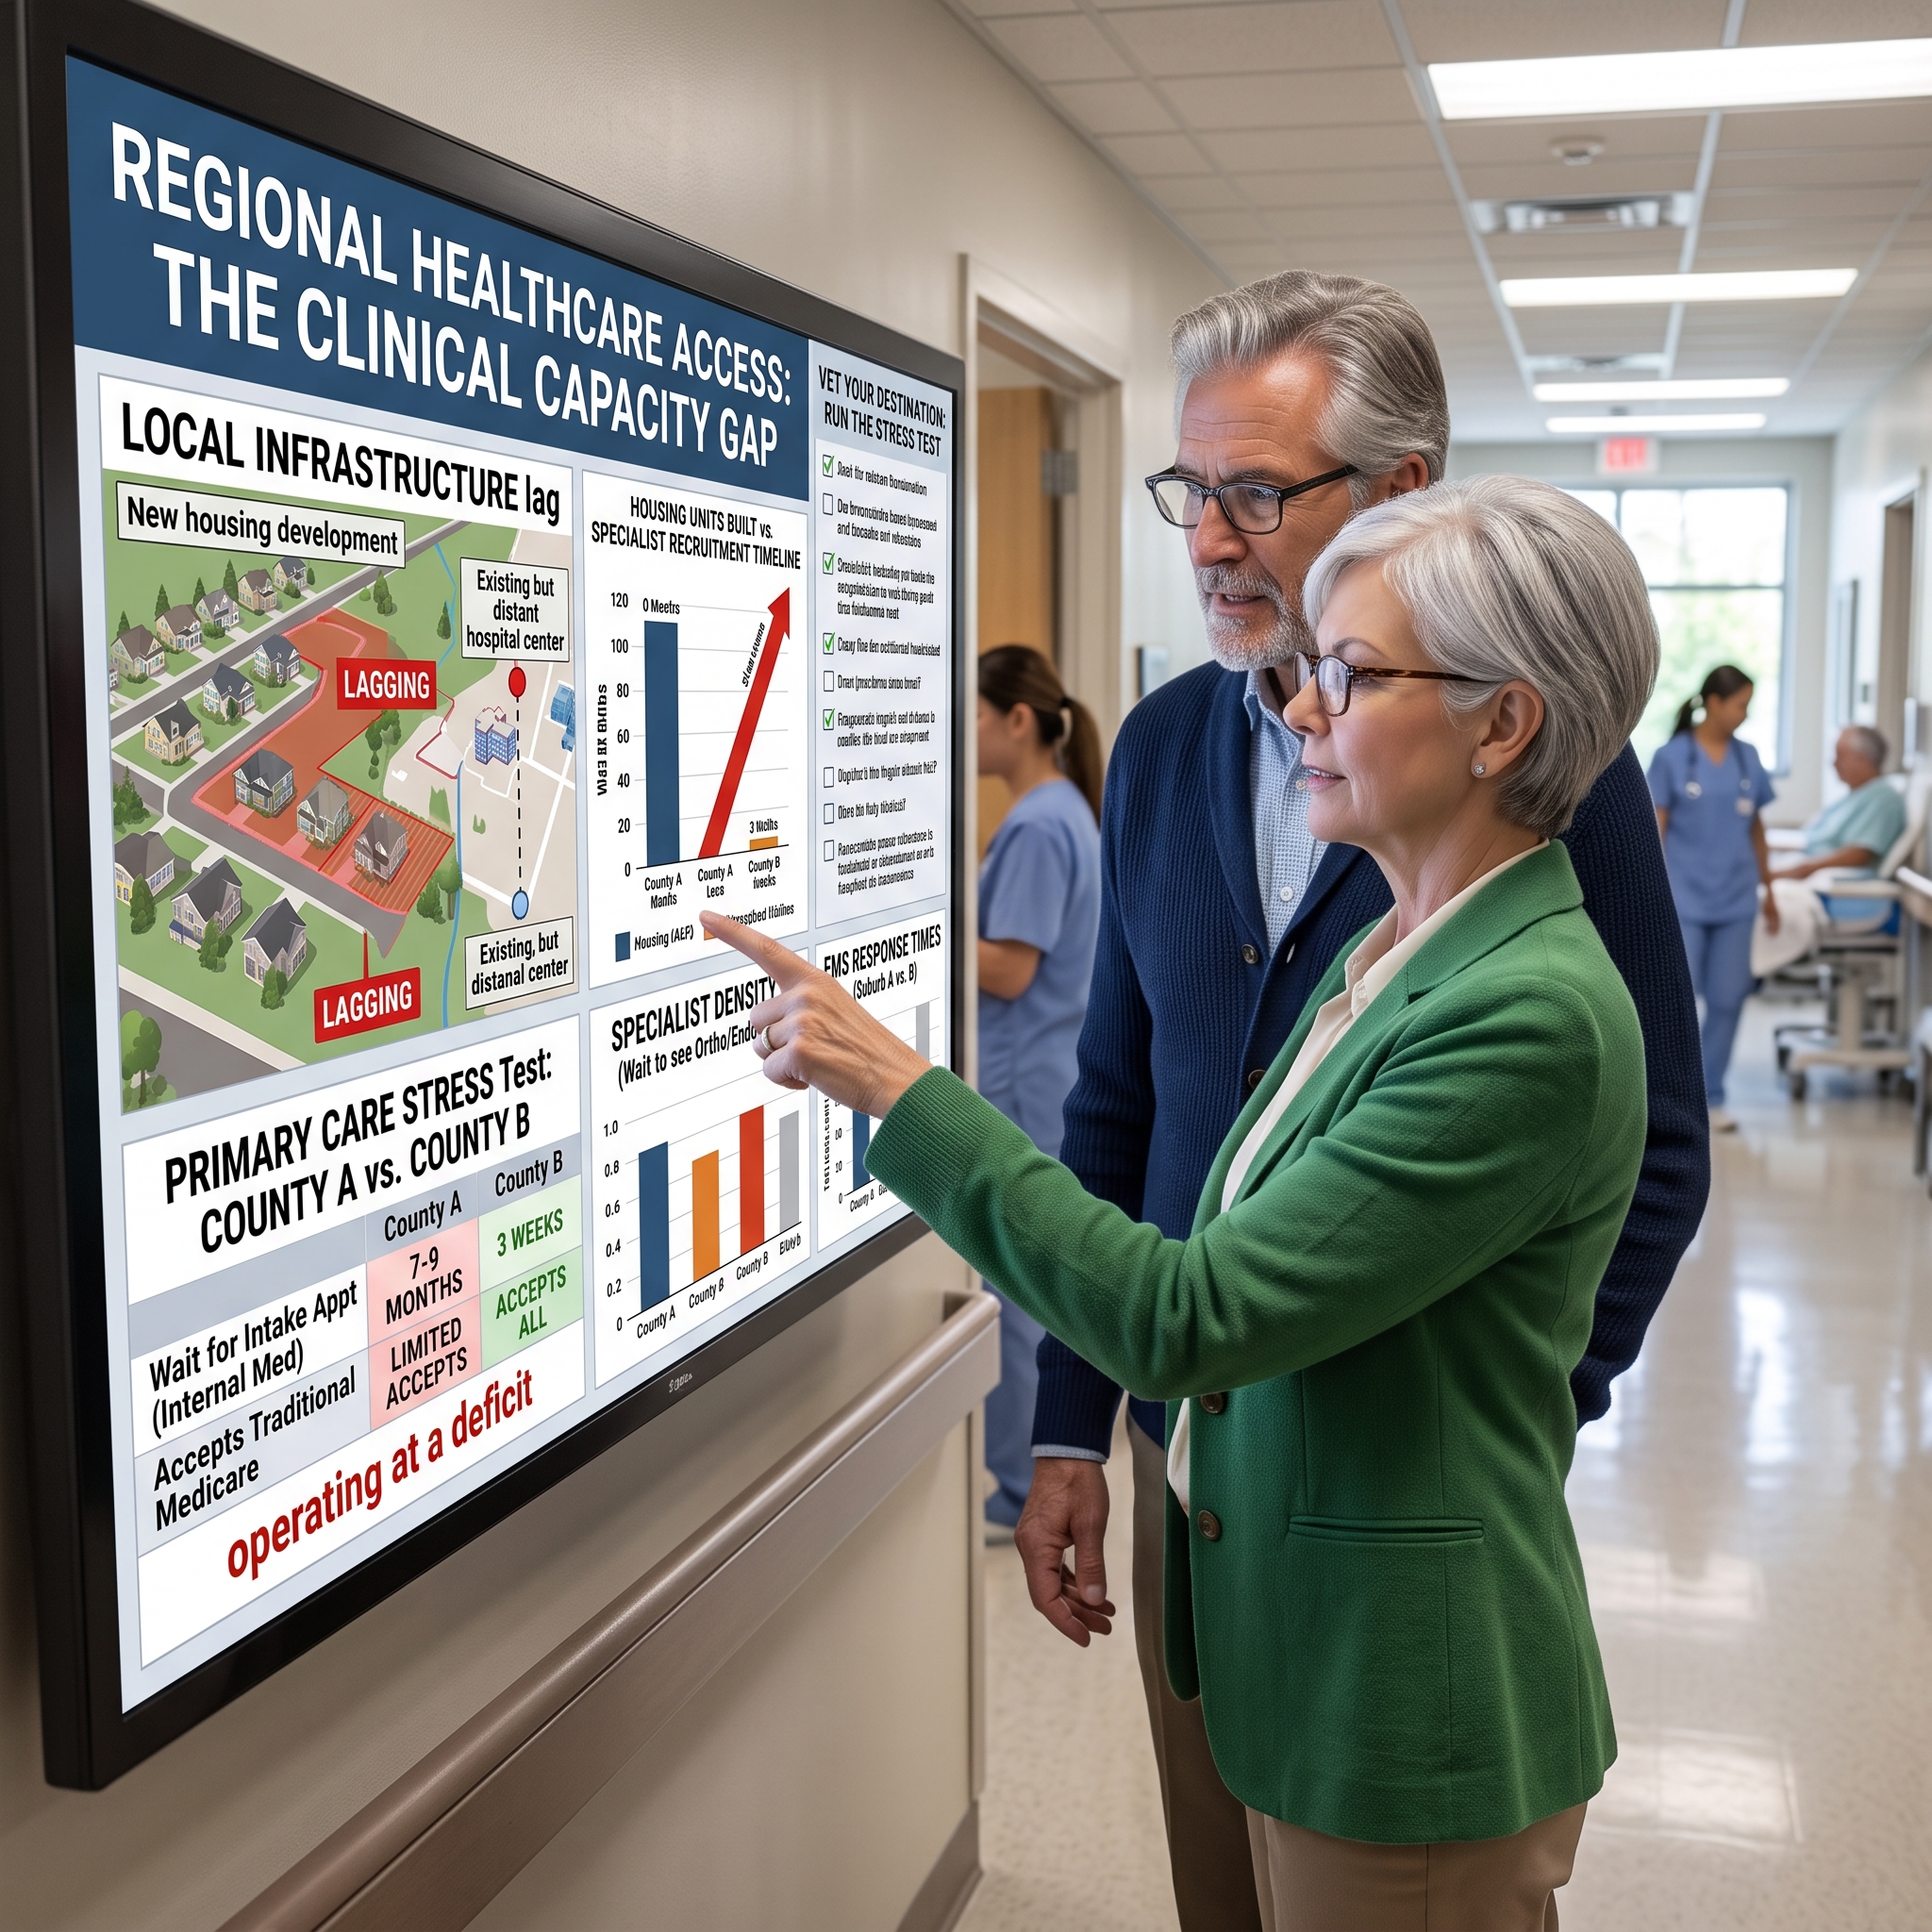
Rapidly expanding retirement destinations often experience severe medical infrastructure lag. A homebuilder can throw up several hundred houses in a year, but expanding a regional hospital wing, adding specialist practices, and recruiting qualified primary care physicians takes years of capital investment and credentialing.
If you move into a market where population growth has outpaced clinical capacity, you may find that scheduling an intake appointment with a board-certified internal medicine physician takes seven to nine months.
Before you make a final commitment to a town, run a Healthcare Stress Test:
Direct Practice Calls: Call three local primary care clinics near the neighborhood you are evaluating. Ask their intake coordinators a straightforward question: "What is the earliest available new-patient appointment for an adult on traditional Medicare and a Medigap plan?" If the answer is half a year away, that medical corridor is operating at a deficit.
Specialist Density: If you manage a chronic health condition (such as cardiac health, rheumatoid issues, endocrinology, or orthopedic concerns), locate the nearest specialized academic medical center. Is it twenty minutes away, or does visiting your specialist require a two-and-a-half-hour highway trek each way?
EMS and Emergency Response: In unincorporated suburban developments and rural pockets, emergency medical response times can vary significantly. Find out whether the local fire and rescue station is staffed full-time with paramedics or relies on volunteer coverage or a regional county squad based miles away.
The Real Estate Strategy: Right-Sizing and Long-Term Liquidity
Selling a long-term family residence to buy a retirement home requires shifting your mindset from speculative appreciation to capital preservation, manageable overhead, and ease of ownership.
Finding the Square Footage Balance
One of the most frequent regrets among relocated retirees is downsizing too aggressively. Moving from a 3,200-square-foot two-story home directly into an 1,100-square-foot cottage often creates severe daily friction. You go from having dedicated personal space, private storage, and room for hobbies to bumping elbows and stacking boxes.
For many couples, an optimal range sits between 1,800 and 2,400 square feet. This layout provides:
Complete single-story main living (primary suite, laundry, kitchen, garage access, and common rooms on one floor).
A dedicated office or multi-purpose workspace.
One or two guest rooms for visiting children or grandchildren that can be closed off and zoned down on the thermostat when not in use.
Universal Design Without the Clinical Feel
Smart residential choices in retirement are about functional architecture, not institutional equipment. Prioritize features that make day-to-day livingeffortless now and safeguard your mobility down the road:
Zero-Threshold Entries: At least one entryway, typically through the garage or covered front porch, with no steps or trip hazards.
Wide Hallways and Interior Openings: Doors measuring 36 inches wide allow easy movement of furniture, luggage, or mobility aids.
Walk-In Curbless Showers: Eliminating high-walled tub surrounds in the primary bath removes the single most common location for domestic slips and falls while improving aesthetic resale value.
Manageable Outdoor Footprint: Look for smaller, well-drained lot footprints with minimal required lawn care, or communities where exterior maintenance is covered by reasonable, stable fees.
Preserving Resale Liquidity
Never buy a property with eccentric floor plans, severe topography issues, or hyper-niche modifications that appeal to only a tiny sliver of future buyers. Life can shift quickly. A sudden medical change or a desire to be closer to family may require you to sell your property in four to seven years.
Buying a clean, well-built home with broad appeal in a high-demand school district or a well-managed adult community ensures that if you decide to pivot, your home can be liquidated efficiently without steep discounting.
Action Plan: The Step-by-Step Relocation Framework
Executing a clean relocation requires deliberate pacing. Spreading your preparation over a multi-stage timeline removes emotional impulse and grounds every decision in verified data.
Stage | Strategic Objective | Primary Action Items |
Phase 1: Financial & Tax Audit | Establish true baseline costs | Calculate combined state income, sales, and property tax liabilities. Run preliminary home and flood insurance quotes on prospective ZIP codes. Calculate net equity from your current residence. |
Phase 2: The Off-Season Audit | Test daily living conditions | Rent a standard residential home for two to four weeks during the target area's worst climate season (August humidity in the Southeast, January cold in the mountains). Avoid resorts; buy groceries, navigate rush-hour routes, and run daily errands. |
Phase 3: Capacity & Service Vetting | Verify critical local infrastructure | Call local primary care clinics to verify patient intake timelines. Check the county planning commission for major road construction, utility expansions, and rezoning filings near your target neighborhoods. |
Phase 4: Representation & Execution | Secure vetted local guidance | Partner with an experienced, full-time local real estate professional who focuses on relocation advisory. Connect with Keith, he has over 140,000 vetted agents across the country who understands micro-market valuations, and provides unvarnished insight on flood risks, HOA reserves, and contract terms. |
Moving Forward With Confidence
Relocating in retirement should never be about running away from winter or hoping that a change in geography will solve everyday personal challenges. It is about intentionally choosing an environment where your financial resources go further, your daily living friction drops, and you have the health and community infrastructure to support your lifestyle for decades.
When you strip away marketing illusions, scrutinize the true costs of ownership, and make your decisions based on verifiable facts, you take complete control of the process. That is how you protect your hard-earned equity, avoid expensive missteps, and successfully settle into Your Next Best Place.
-KeithLucas, Retirement Relocation Strategist™
