The Relocation Calculation:
How to Choose Your Next Best Place Without Blowing Up Your Balance Sheet
Retirement relocation is often sold as a sun-drenched fantasy. You pack a moving truck, head south or west, cash out high-priced equity from the Northeast or Midwest, and spend the next thirty years lounging on a patio with a cold drink.
That picture makes for great television, but it is not how real-world relocation works.
When you relocate in your sixties, you are not taking an extended vacation. You are executing an irreversible financial transaction and fundamentally altering your daily operational reality. The cost of a bad move is staggering. If you sell your paid-off home, buy in an unfamiliar market, realize within eighteen months that you hate the humidity, the traffic, or the medical infrastructure, and then try to move back, the frictional costs alone can easily wipe out $60,000 to $100,000 of your retirement capital. Between real estate commissions, transfer taxes, title fees, moving vans, and new furnishings, a relocation mistake is a self-inflicted financial wound that most nest eggs cannot absorb twice.
Finding your Next Best Place requires ignoring the sales brochures and running the numbers with hard-nosed logic. If you want to make a relocation that improves both your quality of life and your long-term balance sheet, you need a disciplined framework.
The Illusion of the Zero-Tax State
The single most common motivation retirees cite for moving across state lines is taxes. People in high-burden states like New York, New Jersey, California, and Illinois look at states like Florida, Tennessee, Texas, or Nevada and assume their cost of living will instantly plummet because the state income tax is zero.
States require revenue to operate. If a state does not collect income tax, it will balance its budget through property taxes, sales taxes, excise taxes, tolls, or municipal utility fees.
Take Texas, for example. Texas has no personal income tax, which sounds enticing on paper. However, effective property tax rates in Texas frequently hover between 1.6% and 2.2% or higher, depending on the school district and local municipal utility district (MUD) taxes. On a $550,000 home, your annual property tax bill could easily land between $9,000 and $12,000 a year. Contrast that with a state like South Carolina, which taxes income but offers a generous retirement income deduction and caps primary residence owner-occupant property taxes through Act 388 at a fraction of that rate, often resulting in property taxes under $2,500 on an equivalent home.
When you calculate your tax exposure, you must measure your aggregate household tax liability, not just a single line item:
Pensions and Defined-Benefit Plans: Does the destination state tax private pensions, military pensions, or public employee retirement funds?
401(k) and IRA Distributions: Are tax-deferred withdrawals treated as regular income, or is there a senior exemption threshold?
Social Security Taxation: Over thirty states exempt Social Security entirely, but several still tax it based on adjusted gross income.
Property Tax Reassessments: In states like Florida, the "Save Our Homes" cap limits annual assessment increases for existing residents, but when you buy that property as a newcomer, it reassesses to full market value. Never look at what the current owner is paying on Zillow. Your tax bill in Year Two will be based on the purchase price you paid.
Sales and Local Option Taxes: A 7% state sales tax combined with a 2.5% county or municipal levy means you are paying nearly 10% on every purchase outside of basic groceries.
Taxes are a math problem. Run your actual withdrawal figures through the destination state's complete code before you pack a single box.
The Phantom Carrying Costs: Insurance and HOAs
Over the past three years, the real estate landscape has permanently shifted in high-migration corridors. The baseline purchase price of a home is no longer the metric that determines whether an area is truly affordable. The danger lies in the phantom carrying costs: homeowners insurance, flood insurance, and Homeowners Association (HOA) dues.
If you are looking at coastal markets in Florida, Georgia, the Carolinas, or the Gulf Coast, property insurance is undergoing an unprecedented restructuring. Reinsurance rates have driven standard premiums through the roof, and major national carriers have pulled back or non-renewed policies across entire ZIP codes.
Before making an offer on any home near water or in wildfire-prone western regions, you need written quotes from local independent insurance brokers. A $450,000 home with an annual hazard, wind, and flood insurance package running $7,000 a year adds roughly $580 a month to your overhead without building a single dollar of equity.
Similarly, do not gloss over HOA covenants and reserve studies. Master-planned communities offer fantastic amenities like pickleball complexes, resort-style pools, and clubhouse dining, but those amenities require capital upkeep.
When evaluating an HOA community:
Inspect the Reserve Study: Demand the latest reserve study from the seller. If the reserve fund is funded below 70%, a special assessment for roofing, paving, or pool resurfacing is lurking in the near future.
Review Five-Year Fee Escalations: Has the monthly fee climbed 5% a year, or did it double overnight due to commercial landscaping and insurance cost increases?
Examine Architectural Restrictions: Check the rules on parking, golf carts, exterior modifications, and renting the home if your plans change.
Healthcare Capacity: The Metric Most Retirees Ignore
Everyone remembers to check the weather, but almost no one checks the local healthcare capacity until they wake up with an urgent medical issue.
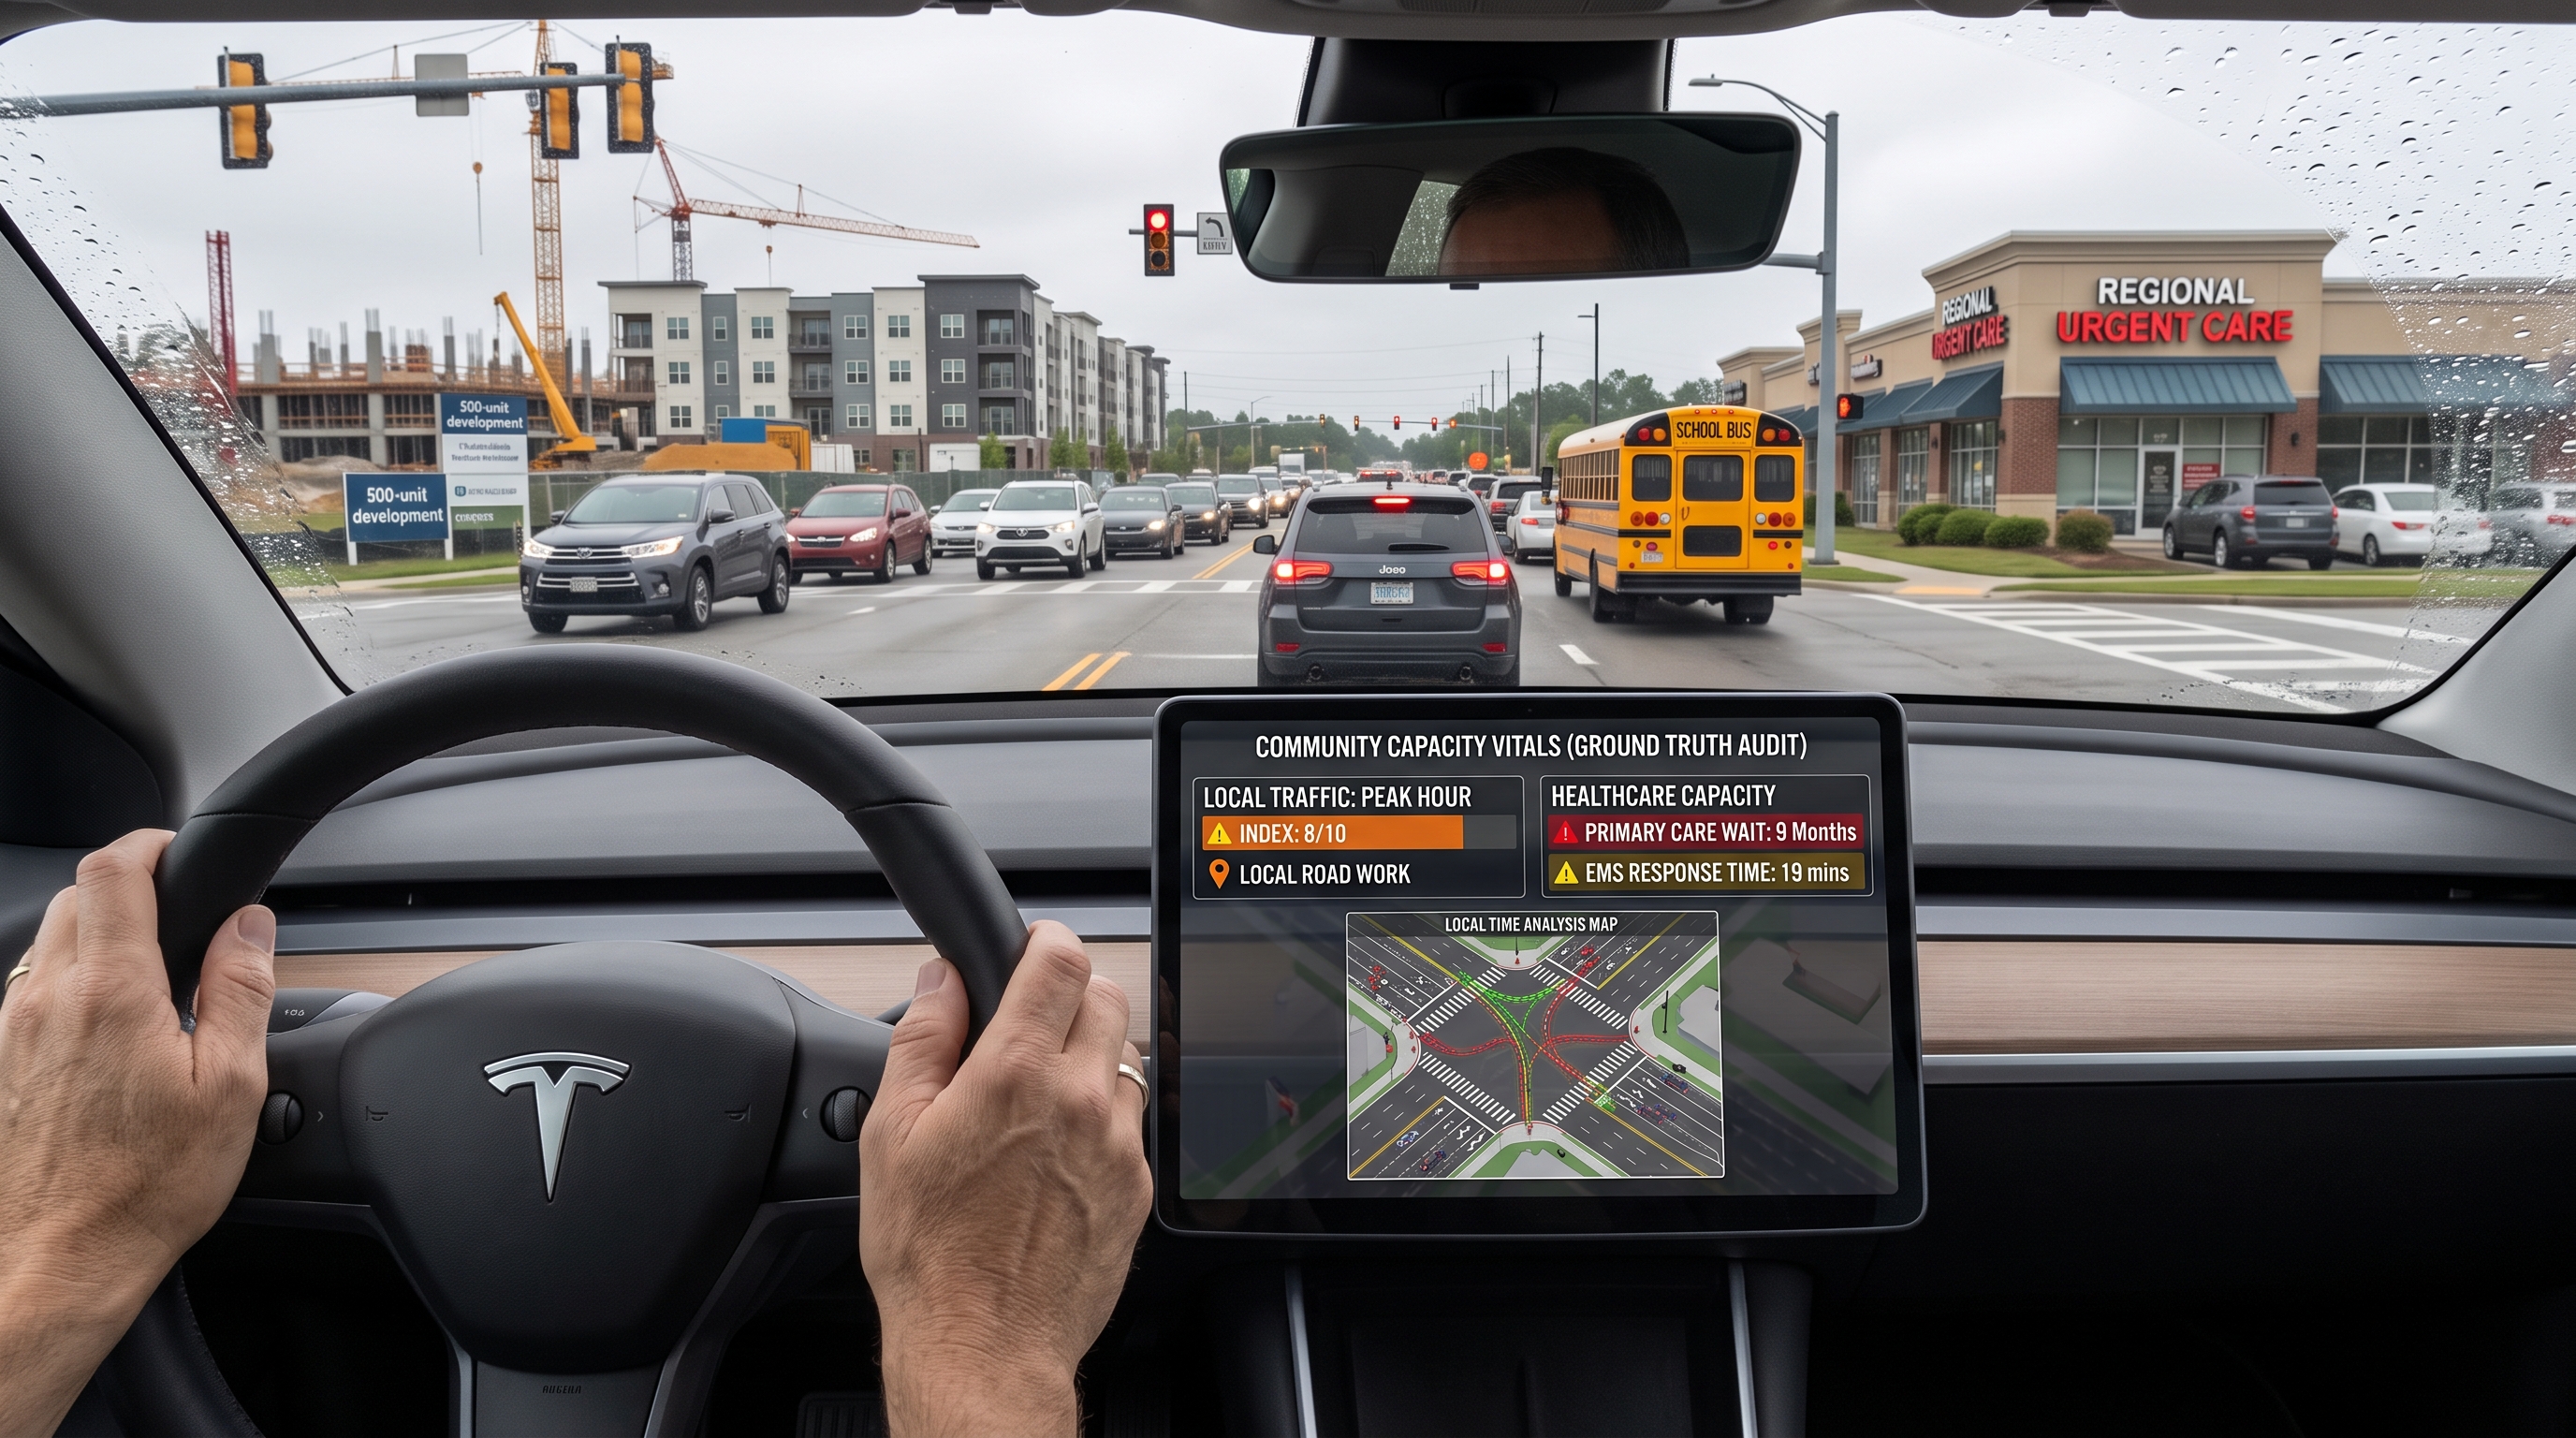
A region experiencing explosive population growth usually faces a severe lag in municipal and medical services. Builders can put up 2,000 homes in eighteen months, but building a hospital wing, credentialing specialists, and recruiting primary care doctors takes five to ten years.
Having a regional hospital thirty minutes down a scenic two-lane highway does not mean you have accessible healthcare. If that hospital does not have a comprehensive cardiac catheterization lab, an accredited stroke center, or adequate orthopedic coverage, you will be transported hours away when seconds count.
Before committing to a relocation market, execute a Healthcare Stress Test:
Call Three Primary Care Practices: Pose as a prospective new resident and ask what the current wait time is for an intake appointment for a patient on Medicare. If the answer is six to nine months, that market is operating under severe clinical strain.
Verify Specialist Networks: If you have an existing chronic condition (cardiology, rheumatology, endocrinology, neurology), find out where the nearest major academic medical center is located. Are you thirty minutes from care, or will you have to drive two hours into a major metro hub every ninety days?
EMS and Fire Response Times: In rural or semi-rural master-planned developments, emergency medical services are often staffed by volunteer fire departments or covered by a county ambulance service stationed fifteen miles away. Ask the local fire district what their average response time is to the neighborhood you are considering.
The Real Estate Strategy: Downsizing Without Sacrificing Liquidity
When selling your long-term family home and buying for retirement, your mindset must shift from asset appreciation to capital preservation and operational liquidity.
Beware Over-Downsizing
The idea of downsizing to an 1,100-square-foot cottage sounds romantic when you are tired of vacuuming four bedrooms and mowing an acre of grass. However, extreme downsizing often creates immediate friction. If you have spent thirty years living in 3,000 square feet, moving into a space where you and your partner are constantly on top of each other leads to rapid buyer's remorse.
A sweet spot for many couples is between 1,800 and 2,400 square feet. This provides single-level living, a dedicated home office or hobby room, and a separate guest bedroom for visiting adult children or grandchildren, while eliminating wasted formal living and dining spaces.
Architectural Longevity Over Cosmetics
Granite countertops and fashionable light fixtures are cheap to change. The underlying floor plan is not. When evaluating prospective properties, prioritize universal design elements that will keep you independent in your home for decades:
Zero-Step Entry: At least one entrance (usually through the garage or front porch) with no steps or trip hazards.
Single-Story Living: The primary suite, laundry room, kitchen, and primary entertaining areas must all be on the ground floor. If there is a second level, treat it strictly as guest or storage space.
Doorway Clearances: Hallways and interior doors should measure 36 inches wide to accommodate mobility aids without drywall damage.
Walk-In, Curbless Showers: Step-over tub thresholds are the number one site of household slip-and-fall injuries among older adults. A curb-free tiled shower is both safer and significantly more attractive to future resale buyers.
Prioritize Resale Liquidity
Never buy a home so quirky, remote, or customized that only 2% of the market would purchase it from you. Your five-to-ten-year needs may change due to health, family updates, or shifting lifestyle interests. Buying a clean, well-located property with broad market appeal ensures that if you ever need to liquidate and adjust your living situation, you can do so in sixty days rather than eighteen months.
Action Plan: The 90-Day Relocation Playbook
If you are planning to make a move over the next twelve to twenty-four months, follow this structured schedule to keep your transition organized and grounded in real-world facts:
Timeline | Critical Focus | Action Steps |
Days 1 to 30 | Fiscal Audit | Calculate total state and local tax liability across income, sales, and property. Run real insurance quotes on target ZIP codes. Determine your realistic net equity from your current home. |
Days 31 to 60 | The Tuesday Test | Book a two-week rental during the target area's worst climate season (mid-summer in the South, mid-winter in the mountains). Live like a local: buy groceries, run peak-hour errands, test the commute, and visit community centers. |
Days 61 to 75 | Medical and Municipal Vetting | Verify doctor intake wait times, call the local planning department to inspect road widening and commercial development permits, and review HOA reserve documents for target neighborhoods. |
Days 76 to 90 | Execution and Network Building | Schedule acll with Keith to be paired with one of his vetted, full-time local agents who specialize in retirement relocation. Avoid transactional agents; partner with professionals who understand local micro-markets, flood zones, and resale dynamics. |
Moving Forward with Purpose
Relocating in retirement is not about running away from a cold winter or an onerous tax bill. It is about actively designing an environment that supports your health, protects your wealth, and gives you the freedom to spend your time doing what brings you fulfillment.
Do not let emotional vacation thinking steer the wheel. Take your time, demand hard numbers, look beneath the surface of the communities you evaluate, and build a concrete plan before you plant your flag. When you approach your relocation with structure and clarity, you turn what could be a stressful gamble into a well-executed step toward your Next Best Place.
