Welcome to the Blog - Life After Work, With a Side of Truth
Hey there. You made it to the blog, nice job dodging all the clickbait.
Here’s where we talk about what really happens after you clock out for the last time. Retirement isn’t just about golf carts and early-bird specials (though we’re not knockin’ a good buffet). This blog dives into the real stuff, finding purpose, staying sane, and maybe even enjoying yourself a little while Uncle Sam tries to take another bite of your savings.
You’ll find:
Real talk about life after work. Helpful guides on how to retire without losing your mind (or your money) and a ton of listicles, best beach towns, worst tax traps, cheap spots that aren’t dumps, and all the places that either feel like heaven… or smell like regret.
It’s part inspiration, part information, with a sprinkle of sarcasm and a whole lotta heart.
Welcome to the Blog
Life After Work, With a Side of Truth
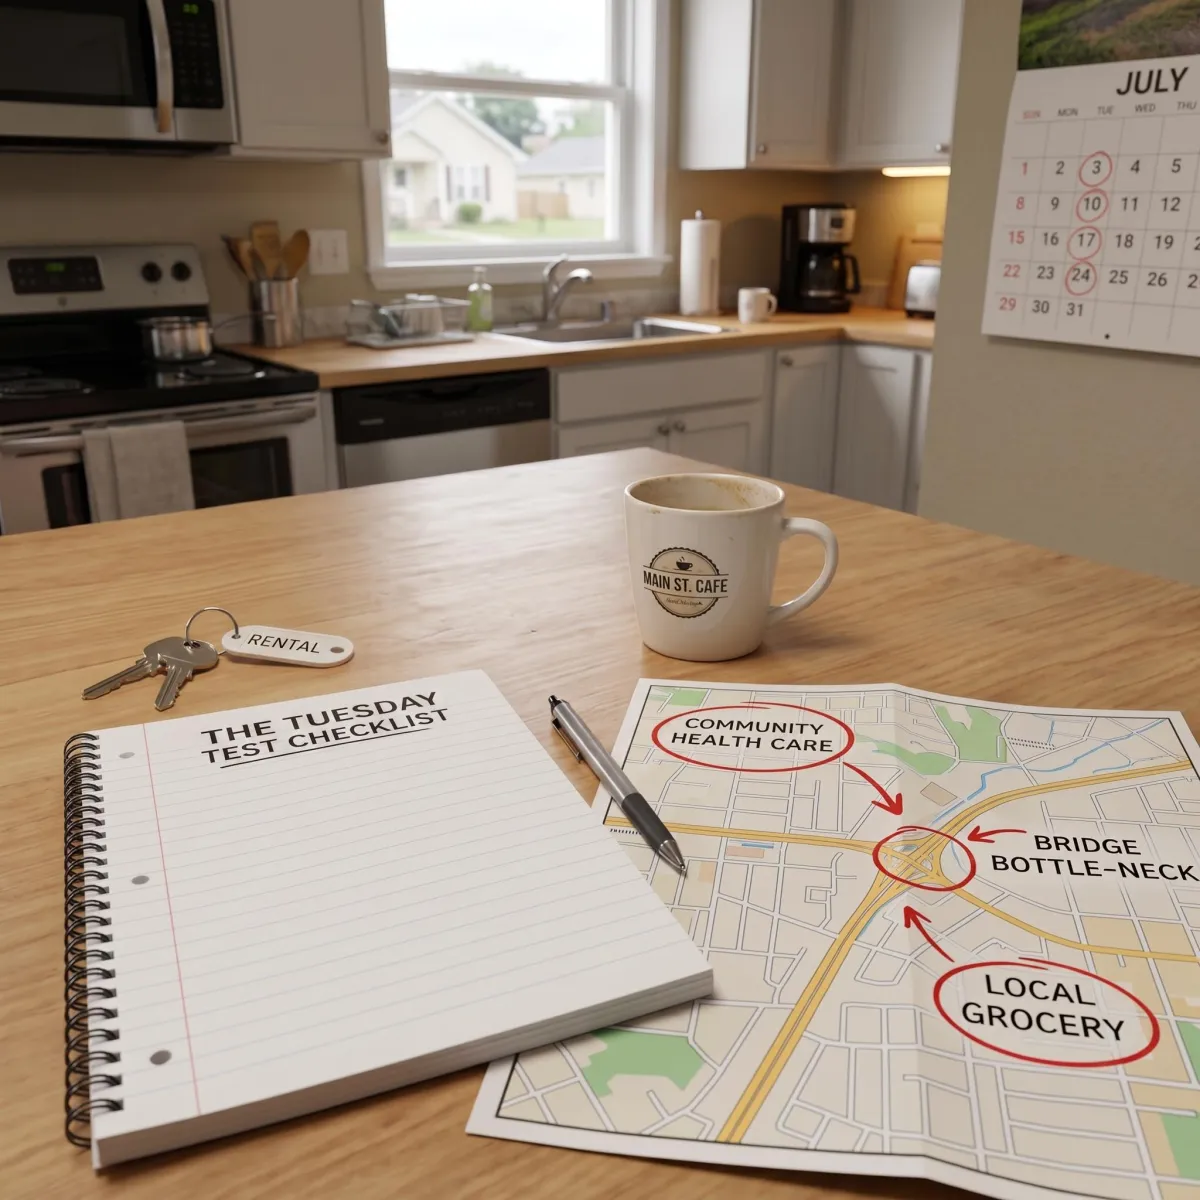
The Tuesday Test
How to Pick Your Next Best Place Without Making a Costly Mistake
Most people plan their retirement moves backward.
They fall in love with a vacation town in the middle of October. The weather is crisp, the leaves are turning, the local seafood place has zero wait, and the rental cottage feels like heaven. By Sunday evening, they are scrolling real estate apps, calculating home equity, and convincing themselves that life will permanently feel like a four-day weekend if they just buy a house near that marina.
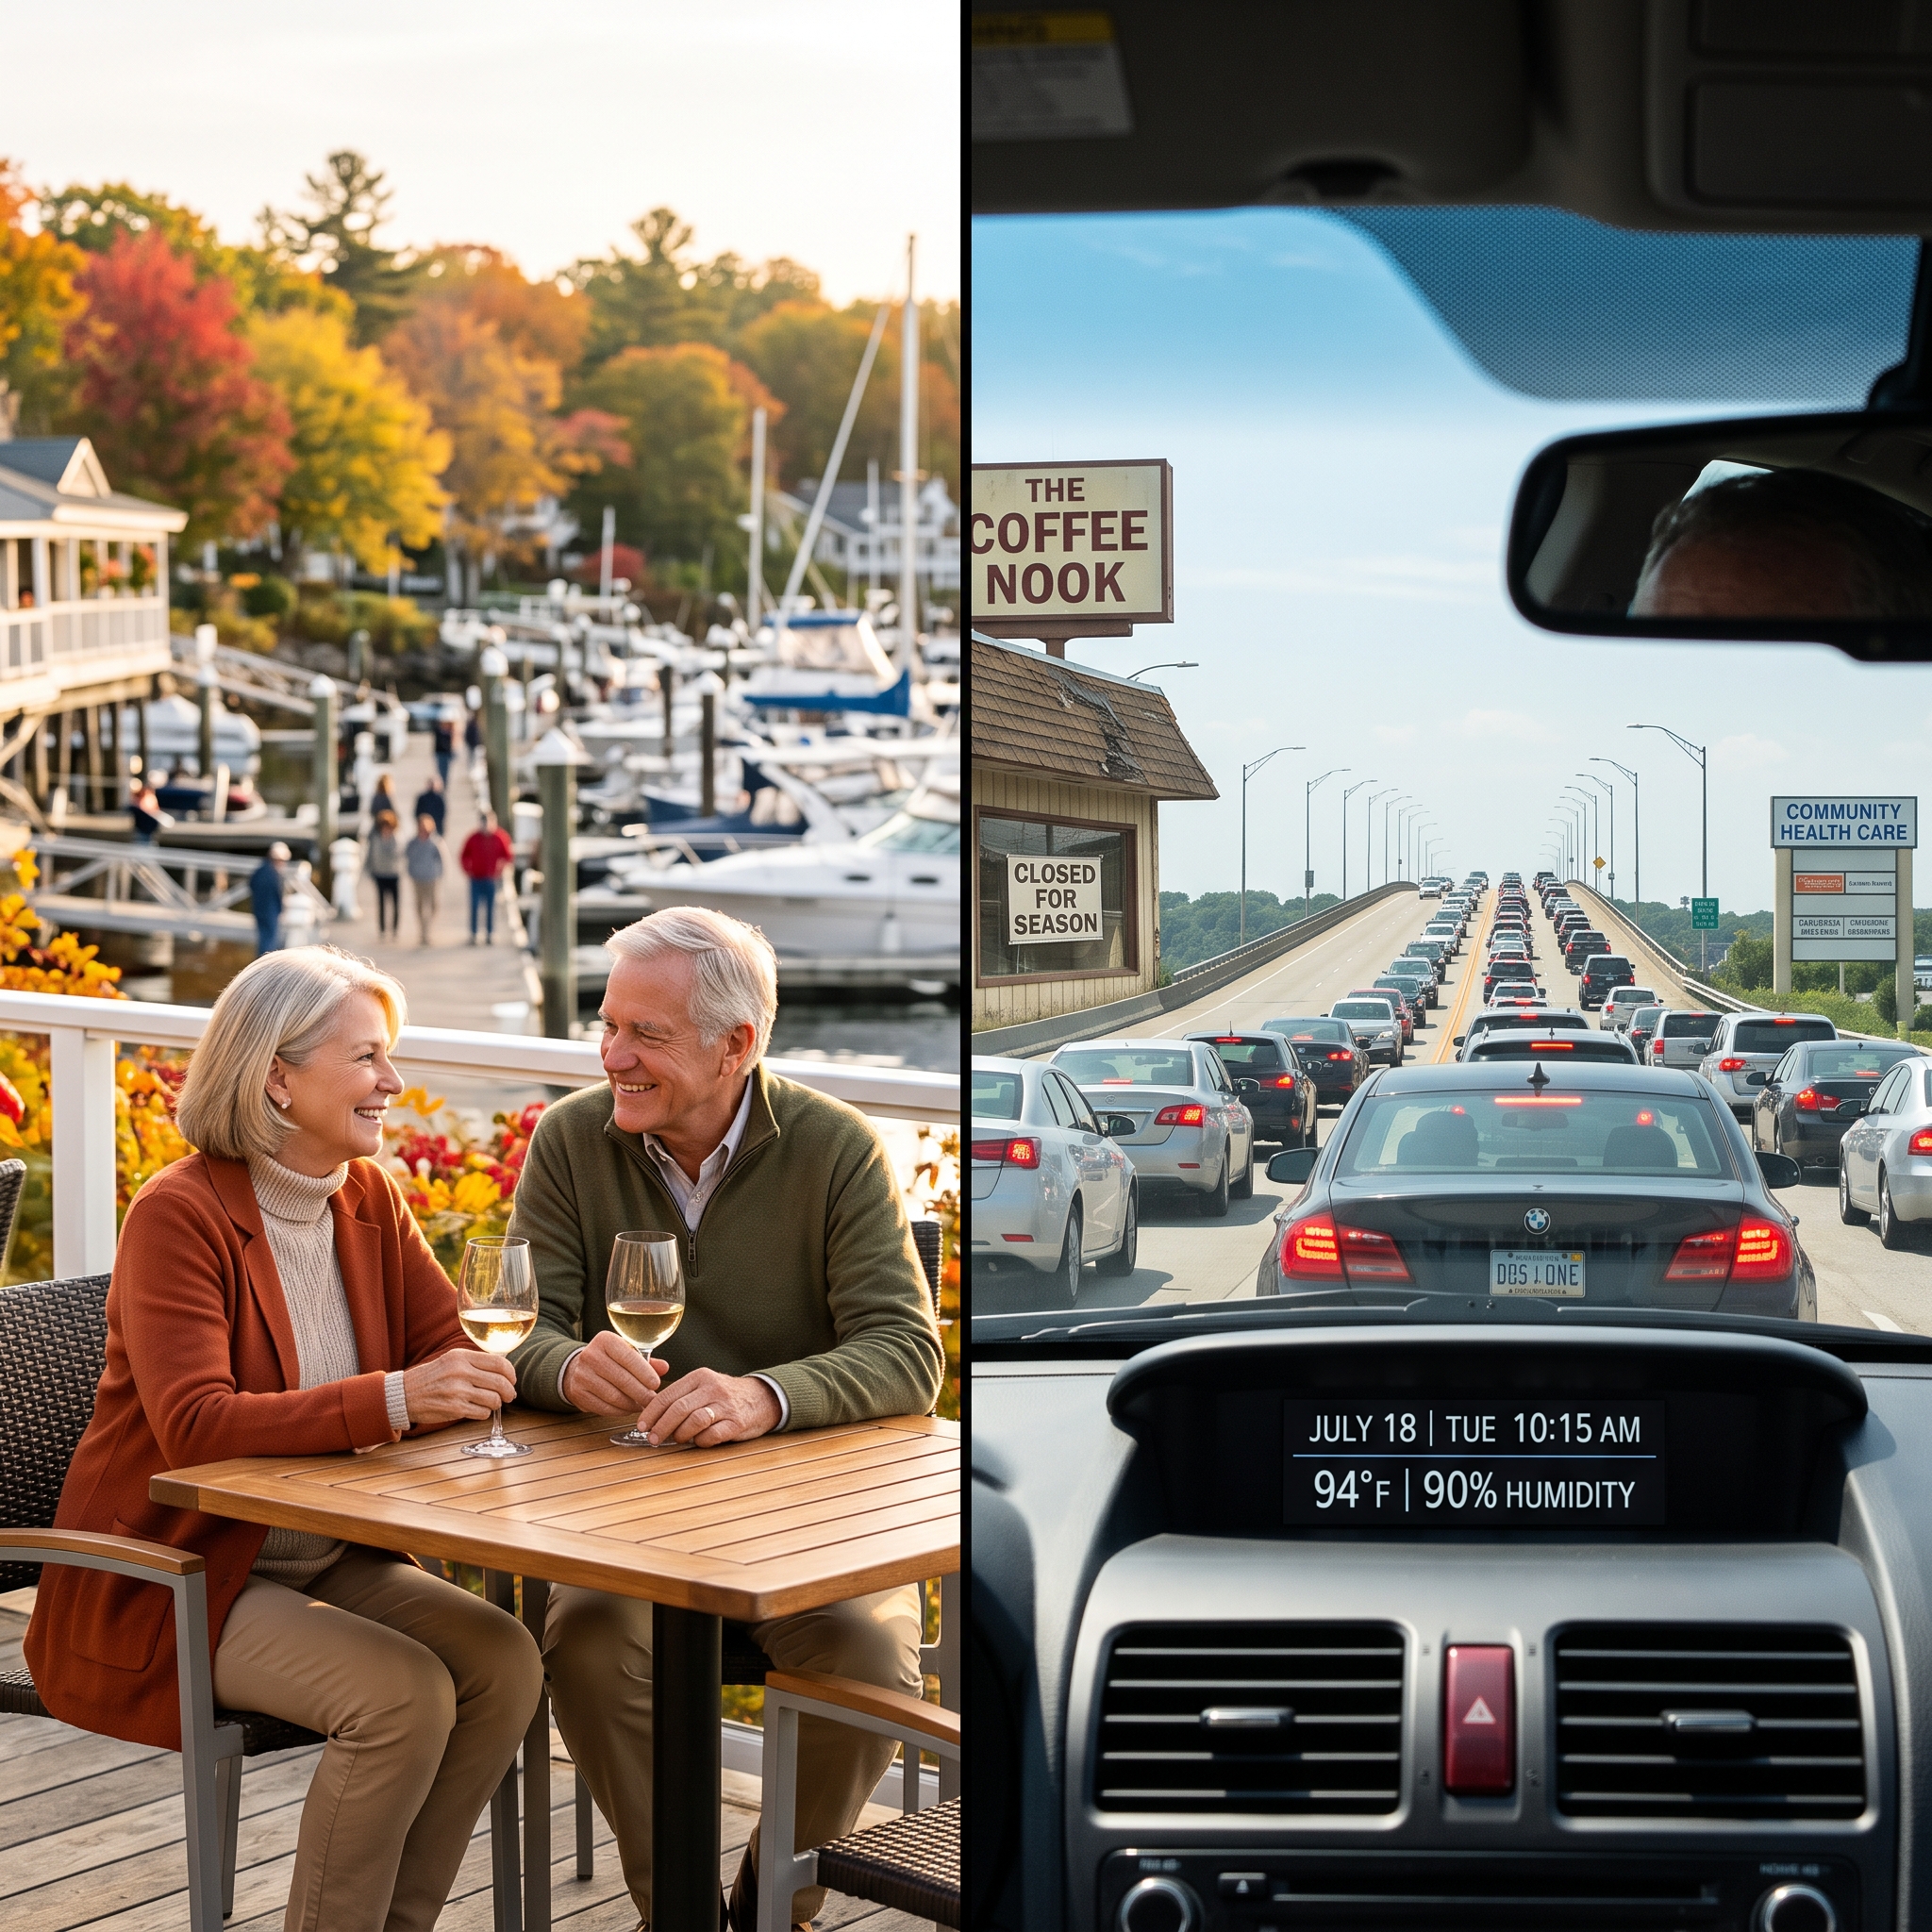
Six months after closing, reality arrives.
It is a Tuesday morning in late July. The humidity is sitting at 90%, the local bridge is backed up two miles with seasonal traffic, the primary care physician they called has an eight-month waiting list for new patients, and the cozy coffee shop from October is closed until spring because the owners only operate during peak tourist season.
Vacation mode is an illusion. Retirement is everyday life.
If you are thinking about moving across state lines, downsizing, or relocating to an entirely new region, you do not need another glossy top-ten list. You need an operational framework. Moving in retirement is one of the largest financial and emotional decisions you will ever make, and getting it right requires looking past the postcards to evaluate taxes, healthcare infrastructure, real estate liquidity, and daily lifestyle rhythm.
Here is the exact playbook to help you find your Next Best Place with clarity and precision.
Phase 1: The Destination Audit
When people start looking at retirement destinations, they usually begin with climate and property prices. While those matter, they are only two pieces of a much larger puzzle. To properly evaluate any potential market, you must run it through five structural filters.
1. The True Tax Picture
Never choose a state based solely on its income tax rate. A state with zero income tax has to generate revenue somehow, and they almost always make up the difference through property taxes, sales taxes, or special municipal assessments.
State income tax on pensions, 401(k) withdrawals, and Social Security.
County and municipal property tax rates, including how reassessments work when a property sells. In many states, the property taxes the previous owner paid have zero bearing on what your bill will be next year.
Local and state sales taxes, especially on groceries, utilities, and prescription medications.
Vehicle ad valorem taxes and annual registration fees.
Estate and inheritance taxes at the state level.
2. Healthcare Capacity and Proximity
Having a regional hospital thirty minutes away is not the same thing as having accessible, high-quality primary and specialized care. In rapid-growth retirement corridors, population growth often outpaces clinical staffing.
Proximity to a Level 1 or Level 2 trauma center.
The local doctor-to-patient ratio for primary care physicians accepting Medicare and Medigap plans.
The presence of dedicated specialist networks (cardiology, orthopedics, neurology, and oncology).
Average emergency room wait times and regional EMS response coverage.
3. Total Cost of Homeownership
The purchase price of a home is just the baseline. In today's market, carrying costs can dramatically shift your monthly budget.
Property insurance availability and annual premium escalation trends.
Flood zone determinations, storm surge vulnerabilities, and elevation certificates.
Homeowners Association (HOA) fees, master association assessments, and reserve fund health.
Utility costs, particularly summer cooling or winter heating baselines.
4. Regional Infrastructure and Growth Pressures
A charming two-lane road might look idyllic on a weekend, but if three new 500-home developments are under construction nearby, your daily drive to the grocery store will quickly become an exercise in frustration.
Planned commercial and residential developments within a five-mile radius.
Road capacity, bridge choke points, and infrastructure funding.
Airport connectivity: How easy is it to get on a non-stop flight to visit children and grandchildren?
5. Daily Community Rhythm
What does the area look like when the tourists go home? What does it look like on a rainy Tuesday morning in the off-season?
Availability of daily essentials (grocery stores, pharmacies, hardware stores, gyms).
Active community groups, clubs, pickleball leagues, and volunteer networks.
Year-round dining and cultural options versus purely seasonal operations.
Phase 2: The Tuesday Test
The single biggest mistake prospective retirees make is buying a home after only visiting an area on vacation. Vacation Keith loves everything: the restaurant food tastes better, the morning walks are longer, and minor inconveniences do not matter because he is on vacation.
To know if an area works for long-term living, you must execute The Tuesday Test.
Rent an ordinary short-term property or apartment for two to four weeks during the worst weather season of the year. If you are looking at Florida or coastal South Carolina, visit in late July or August when the heat and humidity are at their peak. If you are looking at the mountains of Tennessee or North Carolina, visit during the gray freeze of January or February.
During your stay, follow strict rules:
Do not stay in a luxury resort or hotel. Rent a house in a regular residential neighborhood where you are actually considering buying.
Act like a resident, not a tourist. Wake up at your normal time, brew your own coffee, and cook your meals at home.
Run normal errands at peak hours. Drive to the local supermarket at 5:00 PM on a Tuesday. Find the nearest pharmacy. Visit the public library. Drive past the regional medical park at 8:30 AM to see what traffic looks like.
Test the medical ecosystem. Call three local primary care practices and ask what their current intake timeline is for new Medicare patients.
Talk to the locals. Go to the hardware store, the local diner, or the municipal dog park. Ask long-time residents what they love about the area, but more importantly, ask what has changed over the last five years and what frustrates them most about local growth.
If you still love the town after two weeks of buying groceries, sitting in school-zone traffic, and enduring the toughest weather month of the year, it passes the test.
Phase 3: Navigating the Real Estate Transaction
Once an area passes your audit and the Tuesday Test, you enter the execution phase. Real estate transactions in retirement carry different stakes than buying a home during your peak earning years. You are no longer building equity for a future career jump; you are protecting capital, managing cash flow, and positioning yourself for long-term comfort.
Avoid the "Forever Home" Trap
Many buyers put intense pressure on themselves to find the perfect house that will accommodate every hypothetical scenario for the next thirty years. This mindset often leads to analysis paralysis or overspending on square footage they will rarely use.
Focus on your five-to-seven-year horizon. Your needs today (active lifestyle, space for visiting family, proximity to golf or water) may look different fifteen years from now. Buy a property that serves your immediate next chapter well, but make sure it has strong resale liquidity in case your priorities shift down the road.
Critical Home Features for Long-Term Living
You do not need an institutional-looking home, but smart architectural design makes life significantly easier as the years go on.
Single-story living: Even if the home has a second floor or bonus room for guests, the primary bedroom, bathroom, laundry room, kitchen, and garage entrance must all be on the main level with zero steps if possible.
Wide hallways and doorways: Standard 36-inch doors make moving furniture easy and accommodate future mobility needs without expensive renovations.
Curbless primary showers: Walk-in showers without a raised threshold are cleaner, safer, and add substantial resale appeal.
Low-maintenance exterior materials: Fiber-cement siding, composite decking, and drought-tolerant landscaping save thousands of dollars and hundreds of hours of physical labor over time.
Phase 4: Financial and Administrative Transition Checklist
Relocating across county or state lines involves dozens of small administrative details that can easily slip through the cracks. Missing a key deadline can cause tax headaches or lapses in coverage.
Follow this step-by-step checklist to keep your transition smooth and organized:
Step 1: Domicile and Residency Establishment
File a Declaration of Domicile in your new county (if required by your state).
Update your driver's license, vehicle titles, and voter registration within the state's mandatory window (usually 30 to 90 days after moving).
Update your primary address with the IRS, Social Security Administration, and your financial institutions.
Step 2: Legal and Estate Planning Updates
Estate planning documents (wills, revocable living trusts, healthcare directives, and durable powers of attorney) are governed by state law. Have a qualified local attorney review your existing documents to ensure they comply with your new state's statutes.
Check how your new state handles homestead exemptions and file for your property tax exemption as soon as you become eligible.
Step 3: Healthcare and Insurance Coordination
If enrolled in Original Medicare (Parts A and B) with a Medigap (Supplement) policy, your coverage travels with you nationwide, but you must notify your carrier of your address change.
If enrolled in a Medicare Advantage (Part C) or Part D prescription drug plan, moving outside your plan's service area triggers a Special Enrollment Period (SEP). You must select a new regional plan to avoid coverage gaps.
Shop homeowners and auto insurance policies well before your closing date to avoid last-minute financing delays.
Step 4: Banking and Professional Services
Establish a relationship with a local banking branch if you prefer in-person financial services.
Transfer your prescriptions to a local pharmacy and request complete digital records from your previous physicians before you move.
The Path Forward
Finding your Next Best Place is not about chasing an idealized postcard lifestyle. It is about aligning your daily environment, your financial security, and your personal priorities so you can spend your time doing what matters most to you.
Take your time. Do the research. Visit in the off-season. Ask hard questions about taxes, healthcare, and infrastructure. When you base your relocation decisions on real data and practical observation rather than vacation emotion, you set yourself up for a smooth transition and a fulfilling next chapter.
Keith Lucas - Retirement Relocation Strategist™
The Tuesday Test
How to Pick Your Next Best Place Without Making a Costly Mistake
Most people plan their retirement moves backward.
They fall in love with a vacation town in the middle of October. The weather is crisp, the leaves are turning, the local seafood place has zero wait, and the rental cottage feels like heaven. By Sunday evening, they are scrolling real estate apps, calculating home equity, and convincing themselves that life will permanently feel like a four-day weekend if they just buy a house near that marina.
Six months after closing, reality arrives.
It is a Tuesday morning in late July. The humidity is sitting at 90%, the local bridge is backed up two miles with seasonal traffic, the primary care physician they called has an eight-month waiting list for new patients, and the cozy coffee shop from October is closed until spring because the owners only operate during peak tourist season.
Vacation mode is an illusion. Retirement is everyday life.
If you are thinking about moving across state lines, downsizing, or relocating to an entirely new region, you do not need another glossy top-ten list. You need an operational framework. Moving in retirement is one of the largest financial and emotional decisions you will ever make, and getting it right requires looking past the postcards to evaluate taxes, healthcare infrastructure, real estate liquidity, and daily lifestyle rhythm.
Here is the exact playbook to help you find your Next Best Place with clarity and precision.
Phase 1: The Destination Audit
When people start looking at retirement destinations, they usually begin with climate and property prices. While those matter, they are only two pieces of a much larger puzzle. To properly evaluate any potential market, you must run it through five structural filters.
1. The True Tax Picture
Never choose a state based solely on its income tax rate. A state with zero income tax has to generate revenue somehow, and they almost always make up the difference through property taxes, sales taxes, or special municipal assessments.
State income tax on pensions, 401(k) withdrawals, and Social Security.
County and municipal property tax rates, including how reassessments work when a property sells. In many states, the property taxes the previous owner paid have zero bearing on what your bill will be next year.
Local and state sales taxes, especially on groceries, utilities, and prescription medications.
Vehicle ad valorem taxes and annual registration fees.
Estate and inheritance taxes at the state level.
2. Healthcare Capacity and Proximity
Having a regional hospital thirty minutes away is not the same thing as having accessible, high-quality primary and specialized care. In rapid-growth retirement corridors, population growth often outpaces clinical staffing.
Proximity to a Level 1 or Level 2 trauma center.
The local doctor-to-patient ratio for primary care physicians accepting Medicare and Medigap plans.
The presence of dedicated specialist networks (cardiology, orthopedics, neurology, and oncology).
Average emergency room wait times and regional EMS response coverage.
3. Total Cost of Homeownership
The purchase price of a home is just the baseline. In today's market, carrying costs can dramatically shift your monthly budget.
Property insurance availability and annual premium escalation trends.
Flood zone determinations, storm surge vulnerabilities, and elevation certificates.
Homeowners Association (HOA) fees, master association assessments, and reserve fund health.
Utility costs, particularly summer cooling or winter heating baselines.
4. Regional Infrastructure and Growth Pressures
A charming two-lane road might look idyllic on a weekend, but if three new 500-home developments are under construction nearby, your daily drive to the grocery store will quickly become an exercise in frustration.
Planned commercial and residential developments within a five-mile radius.
Road capacity, bridge choke points, and infrastructure funding.
Airport connectivity: How easy is it to get on a non-stop flight to visit children and grandchildren?
5. Daily Community Rhythm
What does the area look like when the tourists go home? What does it look like on a rainy Tuesday morning in the off-season?
Availability of daily essentials (grocery stores, pharmacies, hardware stores, gyms).
Active community groups, clubs, pickleball leagues, and volunteer networks.
Year-round dining and cultural options versus purely seasonal operations.
Phase 2: The Tuesday Test
The single biggest mistake prospective retirees make is buying a home after only visiting an area on vacation. Vacation Keith loves everything: the restaurant food tastes better, the morning walks are longer, and minor inconveniences do not matter because he is on vacation.
To know if an area works for long-term living, you must execute The Tuesday Test.
Rent an ordinary short-term property or apartment for two to four weeks during the worst weather season of the year. If you are looking at Florida or coastal South Carolina, visit in late July or August when the heat and humidity are at their peak. If you are looking at the mountains of Tennessee or North Carolina, visit during the gray freeze of January or February.
During your stay, follow strict rules:
Do not stay in a luxury resort or hotel. Rent a house in a regular residential neighborhood where you are actually considering buying.
Act like a resident, not a tourist. Wake up at your normal time, brew your own coffee, and cook your meals at home.
Run normal errands at peak hours. Drive to the local supermarket at 5:00 PM on a Tuesday. Find the nearest pharmacy. Visit the public library. Drive past the regional medical park at 8:30 AM to see what traffic looks like.
Test the medical ecosystem. Call three local primary care practices and ask what their current intake timeline is for new Medicare patients.
Talk to the locals. Go to the hardware store, the local diner, or the municipal dog park. Ask long-time residents what they love about the area, but more importantly, ask what has changed over the last five years and what frustrates them most about local growth.
If you still love the town after two weeks of buying groceries, sitting in school-zone traffic, and enduring the toughest weather month of the year, it passes the test.
Phase 3: Navigating the Real Estate Transaction
Once an area passes your audit and the Tuesday Test, you enter the execution phase. Real estate transactions in retirement carry different stakes than buying a home during your peak earning years. You are no longer building equity for a future career jump; you are protecting capital, managing cash flow, and positioning yourself for long-term comfort.
Avoid the "Forever Home" Trap
Many buyers put intense pressure on themselves to find the perfect house that will accommodate every hypothetical scenario for the next thirty years. This mindset often leads to analysis paralysis or overspending on square footage they will rarely use.
Focus on your five-to-seven-year horizon. Your needs today (active lifestyle, space for visiting family, proximity to golf or water) may look different fifteen years from now. Buy a property that serves your immediate next chapter well, but make sure it has strong resale liquidity in case your priorities shift down the road.
Critical Home Features for Long-Term Living
You do not need an institutional-looking home, but smart architectural design makes life significantly easier as the years go on.
Single-story living: Even if the home has a second floor or bonus room for guests, the primary bedroom, bathroom, laundry room, kitchen, and garage entrance must all be on the main level with zero steps if possible.
Wide hallways and doorways: Standard 36-inch doors make moving furniture easy and accommodate future mobility needs without expensive renovations.
Curbless primary showers: Walk-in showers without a raised threshold are cleaner, safer, and add substantial resale appeal.
Low-maintenance exterior materials: Fiber-cement siding, composite decking, and drought-tolerant landscaping save thousands of dollars and hundreds of hours of physical labor over time.
Phase 4: Financial and Administrative Transition Checklist
Relocating across county or state lines involves dozens of small administrative details that can easily slip through the cracks. Missing a key deadline can cause tax headaches or lapses in coverage.
Follow this step-by-step checklist to keep your transition smooth and organized:
Step 1: Domicile and Residency Establishment
File a Declaration of Domicile in your new county (if required by your state).
Update your driver's license, vehicle titles, and voter registration within the state's mandatory window (usually 30 to 90 days after moving).
Update your primary address with the IRS, Social Security Administration, and your financial institutions.
Step 2: Legal and Estate Planning Updates
Estate planning documents (wills, revocable living trusts, healthcare directives, and durable powers of attorney) are governed by state law. Have a qualified local attorney review your existing documents to ensure they comply with your new state's statutes.
Check how your new state handles homestead exemptions and file for your property tax exemption as soon as you become eligible.
Step 3: Healthcare and Insurance Coordination
If enrolled in Original Medicare (Parts A and B) with a Medigap (Supplement) policy, your coverage travels with you nationwide, but you must notify your carrier of your address change.
If enrolled in a Medicare Advantage (Part C) or Part D prescription drug plan, moving outside your plan's service area triggers a Special Enrollment Period (SEP). You must select a new regional plan to avoid coverage gaps.
Shop homeowners and auto insurance policies well before your closing date to avoid last-minute financing delays.
Step 4: Banking and Professional Services
Establish a relationship with a local banking branch if you prefer in-person financial services.
Transfer your prescriptions to a local pharmacy and request complete digital records from your previous physicians before you move.
The Path Forward
Finding your Next Best Place is not about chasing an idealized postcard lifestyle. It is about aligning your daily environment, your financial security, and your personal priorities so you can spend your time doing what matters most to you.
Take your time. Do the research. Visit in the off-season. Ask hard questions about taxes, healthcare, and infrastructure. When you base your relocation decisions on real data and practical observation rather than vacation emotion, you set yourself up for a smooth transition and a fulfilling next chapter.
Keith Lucas - Retirement Relocation Strategist™
FOLLOW US
COMPANY
LEGAL
© 2026 Retirement Life USA. All Rights Reserved. Retirement Relocation Strategist and Relocation Blueprint are trademarks of Retirement Life USA. Keith Lucas is a licensed real estate broker and the founder of Retirement Life USA, operating under the proprietary Retirement Relocation Strategist™ advisory framework. This information is produced solely for educational and entertainment purposes and should not be considered a source for financial, accounting, tax, or legal guidance. For advice on financial or legal matters, please seek assistance from a qualified financial advisor or lawyer. Opinions expressed herein are solely those of Retirement Life USA.
Important Notice on Brokerage Relationships: Accessing, viewing, or interacting with this website, the RetirementRelo app, or any associated consultations, calls, or communications does not create an agency or fiduciary relationship between you and any brokerage firm or licensee. Under South Carolina law, until you enter into a written buyer agency or listing agreement, you are considered a customer, and Keith Lucas, Charleston Real Estate Company
and Retirement Life USA are presumed to be acting as a transaction broker, not as your representative.
Youtube
Website
Facebook